How to Set Up a Family Emergency Identity Theft Plan
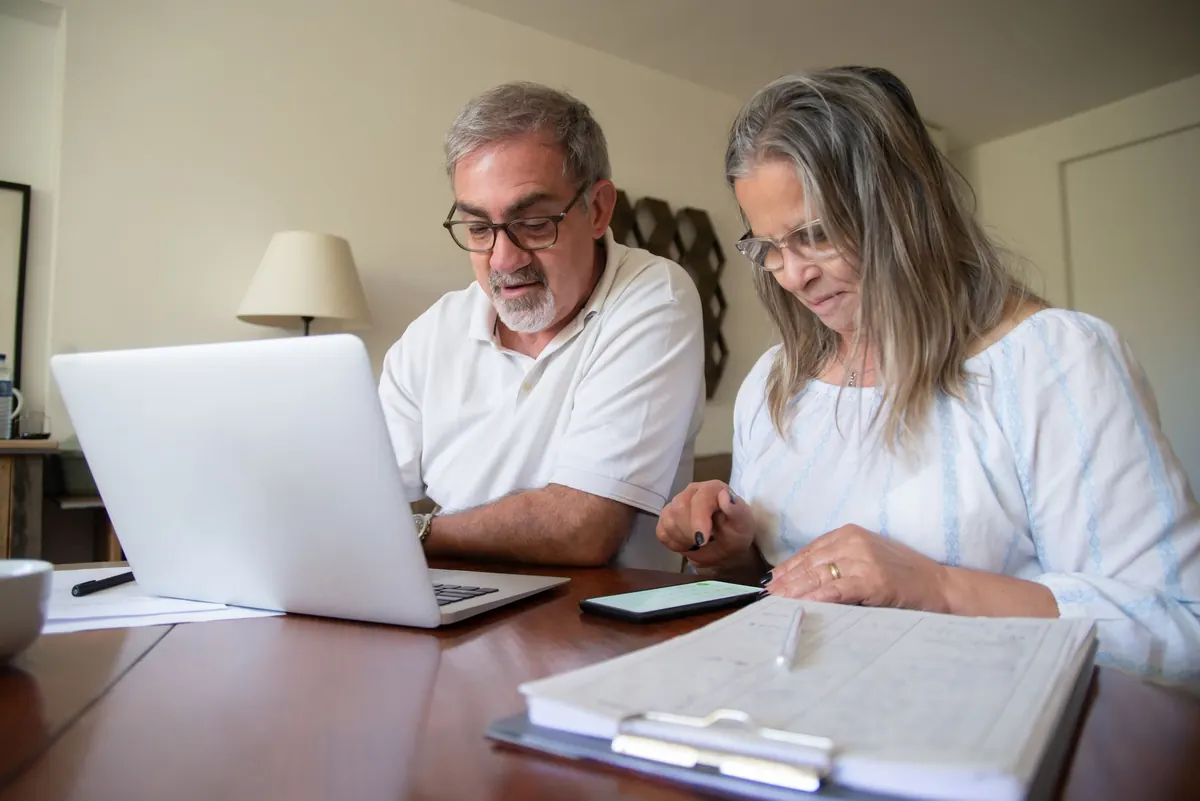
A wallet left on a car seat. A phishing text that looked exactly like a bank alert. A teenager who typed a Social Security number into a scholarship form that turned out to be fake. Identity theft rarely arrives with warning, and when it lands, most households react in five directions at once: one person calls the bank, another cancels a card, someone else digs through a filing cabinet hunting for a policy number nobody can find. A family emergency identity theft plan replaces that scramble with a short list of names, numbers, and steps everyone has already agreed on.
Why One Shared Plan Beats Five Separate Panics
Identity theft tends to touch the whole household even when it starts with one person. Joint bank accounts, a family phone plan, a shared tax filing, a mortgage application, a health insurance policy — all of them can be affected when a single card, email account, or government ID number is compromised.
Two people responding separately can also work against each other. One may place a credit freeze while the other unfreezes it to apply for a loan. Someone may sign up for a paid monitoring service the household already gets free through a bank. Worse, a frightened family member may pay for something that is legally free, like a fraud alert or a credit report.
The fix is not a binder. It is one or two pages that every adult in the house can find in under two minutes, kept both on paper and in an encrypted file. Children old enough to have their own accounts should know the plan exists and who to call, even if they don't hold all the details.
Step 1: Gather What You'd Need at 11 p.m.
When something goes wrong, you don't want to be searching for account numbers. Collect these once, together, and store them where the household agrees they belong:
- Full legal names and any former names used on accounts
- Dates of birth and government ID numbers for each family member, including children
- A list of every bank, credit card, loan, and investment account, with the last four digits and the customer service number printed on the card or statement
- Credit bureau or credit reference agency names and phone numbers for your country
- Insurance policy numbers: health, home, renters, auto, and any identity theft coverage
- The email addresses and phone numbers used for two-factor codes
- Which password manager the household uses, and where the recovery information lives
- Scans or photocopies of passports, driver's licenses, and birth certificates
Store the paper copy in a fireproof safe, a locked drawer, or a bank box. Keep the digital copy in an encrypted file, not in an unencrypted note on a phone. Never email the full document to yourself — email is one of the first things an attacker reads.
Step 2: Assign Roles Before You Need Them
Roles prevent two people from calling the same bank twice while nobody calls the police. Keep it to four jobs and write a name next to each.
The point person
This is the person who reports the theft, files the police report if needed, and keeps a running log of who was called, when, and what was said. One log beats four memories.
The document keeper
They hold the inventory and can pull account numbers, ID copies, and policy details on request. If the point person is the victim and is dealing with a bank hold or a frozen account, this role matters even more.
The money watcher
They monitor shared accounts, watch for unauthorized charges, and handle anything time-sensitive, such as direct deposit changes or a missed bill that could trigger late fees.
The backup
Someone outside the immediate household — a trusted relative or close friend — who knows the plan exists and can step in if the main people are traveling, sick, or simply overwhelmed.
Step 3: Build the Contact List
Print it. Phone numbers that work when the internet is down are worth more than a link. Include the fraud line for each bank and card issuer, the credit bureaus, your local police non-emergency number, your national consumer protection or identity theft reporting body, the tax authority if you file returns, your employer's payroll department, your health insurer, and your utility and phone providers.
Add a few details that people forget: the account number for each card, the name on the account, and whether a fraud alert or freeze is already in place. If a child's information is involved, note that credit bureaus can check whether a file exists in a child's name.
Step 4: The First 48 Hours
- Write down what you know. Date, time, what was lost or exposed, and how you found out. Details fade fast.
- Call the point person. One person starts the log and coordinates the rest.
- Contact the bank or card issuer. Ask them to close or freeze the affected account and to confirm the dispute in writing.
- Change passwords on email, banking, and any account sharing that email address. Turn on two-factor authentication.
- Place a fraud alert or credit freeze with the credit bureaus in your country. A freeze is generally the stronger option if you are not applying for credit soon.
- File a report with the police and with your national identity theft reporting service. Keep the report number.
- Notify payroll, tax, and benefits providers if a government ID number or bank detail was exposed.
- Update the log and tell the backup what happened, so nothing depends on one person's memory.
The Annual Twenty-Minute Review
Once a year, sit down together with the plan open. Check that phone numbers still work, that the account list matches reality, that new family members or accounts have been added, and that anyone who moved out has been removed. Read the roles out loud and confirm everyone still agrees. Do it in January, or on a birthday, or the same weekend you change smoke alarm batteries — the point is to attach it to something you already remember. For legal or financial questions, such as whether to freeze credit or how a dispute affects a loan application, talk to a qualified professional rather than relying on a household document.
Keep It Short Enough to Use
The best plan is not the most thorough one. It is the one your partner can find while you are on hold with the bank, the one your teenager knows to follow if a message looks wrong, and the one that tells your family exactly who calls whom in the first hour. Write it this week, keep two copies, and treat it as a living document. Ten minutes of preparation now saves days of confusion later.
Photo: Kampus Production / Pexels